
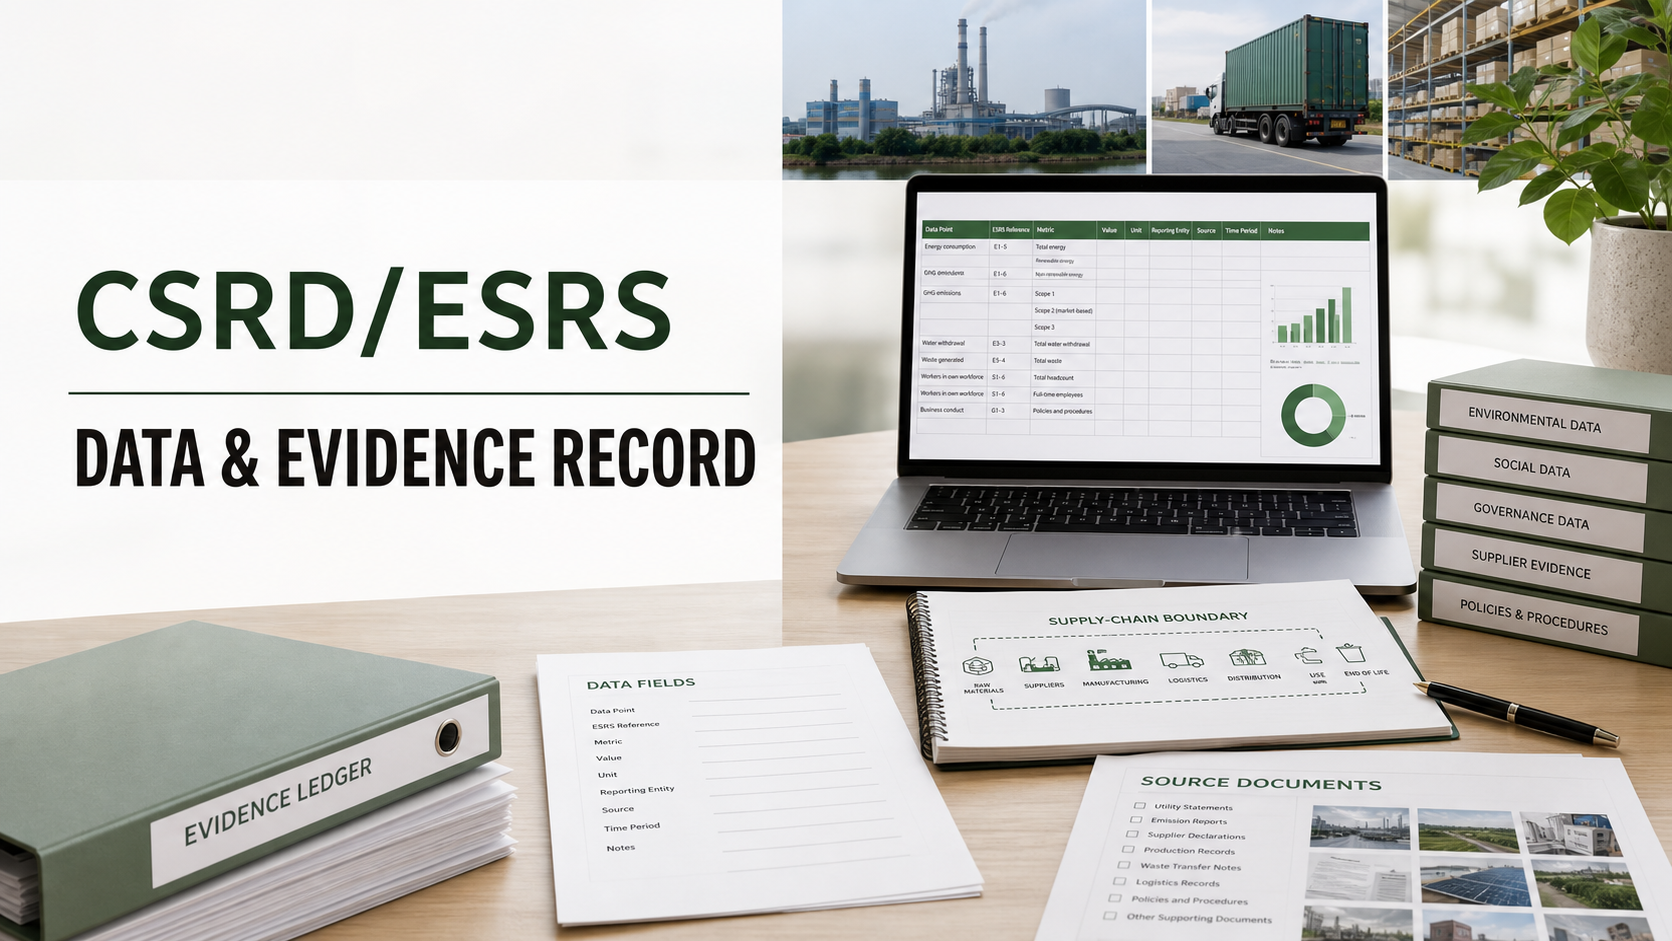
Receiving a CSRD or ESRS questionnaire from a customer does not automatically make a supplier a company subject to the CSRD. A sound preparation process starts by confirming the requesting entity, reporting year, disclosure item and data boundary, then organizing traceable supply-chain information instead of treating one generic certificate as a complete sustainability report.
1. Separate the CSRD, ESRS and the supply-chain request
CSRD is the EU corporate sustainability reporting framework. It requires undertakings within its scope to disclose sustainability-related impacts, risks and opportunities in the management report. ESRS are the European standards used to structure those disclosures. Whether a company reports depends on its legal status, size, listing or public-interest characteristics, group structure and applicable year. It does not depend on whether a supplier holds a particular product certificate.
A cross-border supplier is more often a value-chain data provider. A customer may request information on energy, greenhouse gases, resources, labour or governance for a factory, logistics activity, raw material or product family to support the customer’s own materiality assessment and reporting. The scope should be set by the customer’s questionnaire, contract, data dictionary or supply-chain policy; it does not automatically transfer every ESRS disclosure requirement to the supplier.
ESRS uses a double materiality perspective. One side concerns the actual or potential impacts of the undertaking on people and the environment; the other concerns how sustainability matters create financial risks and opportunities for the undertaking. Before sending data, mark the relevant entity, facility, product or service boundary. “Relevant to the customer” should not be rewritten as “every field is legally mandatory.”
2. Application dates and version boundaries as of August 2026
The European Commission states that the first companies in scope applied the rules for the first time to financial year 2024, with reports published in 2025. Directive (EU) 2025/794, known as the “stop-the-clock” directive, then moved the starting points for later waves: the relevant other large undertakings and large-group parent undertakings moved to financial years beginning on or after 1 January 2027, while relevant listed SMEs and certain other undertakings moved to financial years beginning on or after 1 January 2028. These are reporting-application dates, not a universal deadline for a supplier to answer a customer.
On 3 July 2026 the Commission published delegated acts for revised ESRS and a voluntary standard, but the Commission’s implementing-acts page states that those acts are not in force until publication in the Official Journal. A supplier evidence ledger should therefore record the ESRS version, questionnaire version, reporting year and data cut-off date requested by the customer. It should not present a not-yet-effective simplification text as a single settled legal requirement.
3. Break the questionnaire into five data blocks
The following structure can be used as a supplier worksheet. It does not mean that every customer or every ESRS topic requires every item. Each field should carry its value, boundary, period, source and owner.
1. Entity and reporting boundary: legal name and identifiers, group or subsidiary relationship, production or warehouse locations, facility IDs, product or service scope, customer relationship, coverage period, and any outsourced, leased, consolidated or excluded boundary.
2. Energy and greenhouse gases: energy type, consumption, unit, metered or estimated method, period, facility, emission-factor source, Scope 1/2/3 classification and any product or supply-chain allocation method. If the evidence does not support a precise figure, retain the assumptions and uncertainty instead of inventing precision.
3. Resources, materials, products and packaging: key materials and sources, input quantities, evidence for recycled or recyclable claims, water or waste data, packaging materials and recovery routes. If the customer asks about one product family, identify its product scope, BOM version and facility; do not label company-wide data as a single-SKU figure.
4. Labour and value-chain workers: the relevant supplier or contractor population, occupational health and safety, training, grievance mechanisms, child-labour or forced-labour controls, and audit or remediation records. A social-audit report supports only the locations, period and topics it actually covers; it does not automatically establish that an entire supply chain is risk-free.
5. Governance, policies and targets: environmental or human-rights policies, responsible functions, targets and base year, action plans, supplier onboarding and remediation processes, data review and management approval. If an external assurance or limited-assurance engagement is requested, confirm its scope and acceptable evidence separately.
4. Build a traceable evidence record, not just a number
For each questionnaire field or customer disclosure item, use a unique record. A practical minimum includes the customer question ID; the related ESRS topic or customer metric; data owner; entity, facility, product or service boundary; reporting period; value and unit; calculation method and emission factor; original file name, version, date and storage location; coverage, exclusions and estimation assumptions; reviewer, review date and change history.
For greenhouse-gas or product-allocation data, retain the chain from activity data to result: meter or purchase record → unit conversion → factor and version → allocation rule → reported total. For social or governance information, retain policy versions, training or audit records, remediation closure evidence and applicable locations. Files with the same name but a different version, period or coverage are not the same evidence.
When a factory, supplier or logistics provider supplies the data, record the handoff and confirmation date. When an estimate is used, state why, what inputs and method were used, who approved it and how it may be improved. This allows the customer to distinguish measured, calculated, estimated and externally verified information, and to identify which fields need recalculation when the questionnaire changes.
5. Six manual checks before submission
First, confirm the customer entity, reporting year, questionnaire version and cut-off date. Second, map each question to a field, owner and source file. Third, check the legal entity, facility, product scope and period for consistency. Fourth, test the units, factors, allocation rules, assumptions and rounding. Fifth, reconcile the figures with purchasing, energy, production, transport or audit records and document what is not covered. Sixth, have business and data owners approve the wording so that “supplier-provided data” is not rewritten as “certified” or “fully compliant with all ESRS requirements.”
When a factory, material, energy source, output level, organization or questionnaire changes, create a new version and preserve the old record. Do not overwrite historical figures; otherwise year-on-year comparisons, boundary changes and customer follow-up questions cannot be explained.
6. Common mistakes and evidence boundaries
A certificate is not a CSRD report. An ISO certificate, social-audit report, product test report or material certification can support only the management system, location, product, period or claim it actually covers. It does not automatically replace emissions data, a double-materiality assessment or the supply-chain fields requested by the customer.
A customer questionnaire is not the legal rulebook. Procurement policies, brand targets, financial-institution requests and ESRS items may appear in the same spreadsheet. Before submission, mark each item as a legal reporting basis, a customer-specific metric or a voluntary supplement. Avoid making a broader legal statement than the evidence supports.
Keep cross-border data within its real boundary. Do not extrapolate one factory’s energy data to all affiliated factories, one product’s material declaration to an entire brand, or an unexplained conversion into an impression of exact compliance. 绿色方舟(深圳)认证有限公司 recommends linking each statement to its original evidence, calculation method and applicable scope.
Official sources and update note
Use the European Commission CSRD page for the policy timeline, Directive (EU) 2025/794 for the later-wave date changes, and the EFRAG ESRS Set 1 page for the standards and supporting material. Before a formal submission, check again whether the revised ESRS delegated act published in July 2026 has entered into force through publication in the Official Journal.


